

Budget Calendar
by MiShell Software Systems
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- $4.95
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
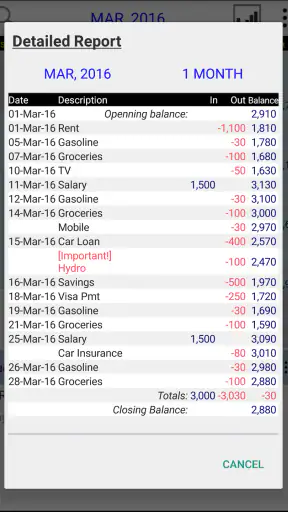
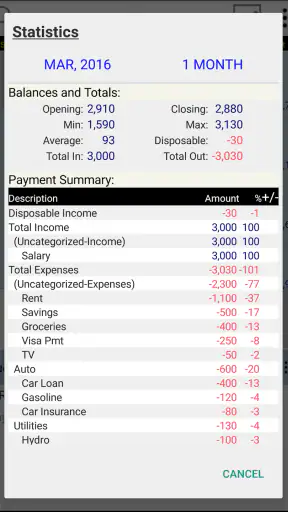
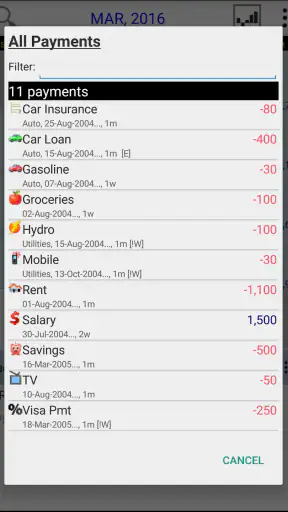
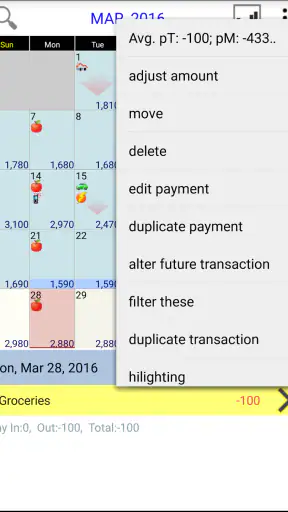
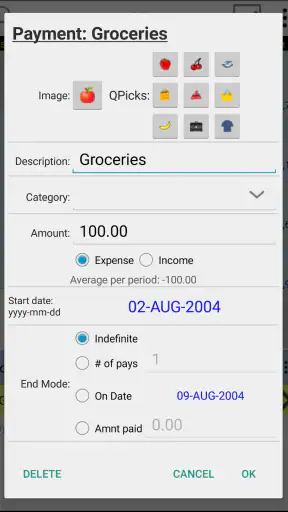
 Analysis by Getfullapps
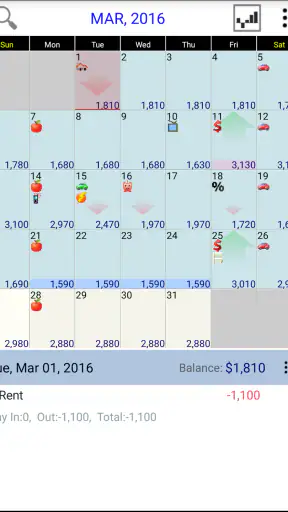
I usually judge a budgeting app by one simple question: does it help me make a decision before I spend money, or does it merely record what happened afterward? Budget Calendar takes the first approach. It is a finance app from MiShell Software Systems that puts planned income and expenses onto a calendar, giving me a forward-looking view of the month instead of forcing me to interpret a list of past transactions.
That difference matters more than it may sound. A normal expense tracker can tell me that I spent too much on food last week. A calendar-based budget can make a bill, payday, subscription, or planned purchase visible in relation to everything else. In my experience, that makes the app especially interesting for people whose main problem is timing rather than a lack of awareness.
My overall recommendation is quite specific: Budget Calendar is worth considering if you think about money in dates and upcoming commitments. It is less convincing if you want a fully automated financial dashboard, investment analysis, or a modern account-syncing experience. The app is paid, priced at $4.95, and its value depends on whether you will actually maintain the calendar.
How I would decide whether Budget Calendar fits
I’d judge the fit by whether a calendar changes a decision I make every month, not by how useful it feels during the first few days. I’d try planning one ordinary stretch between paydays and see whether the dates make a tight week easier to spot. That gives me a practical basis for deciding whether this deserves a regular place in my routine.
A calendar changes the budgeting question
Most budgeting tools organize money by category: groceries, transport, rent, entertainment, and so on. That structure is useful, but it can hide a cash-flow problem. Someone may have enough money for the month in total and still feel short during a particular week because several payments arrive together.
Budget Calendar approaches that problem from the date outward. I can think in terms of “what will happen before the next payday?” rather than only “how much have I spent on this category?” That makes it a practical choice for people with irregular paydays, clustered bills, school-related costs, or recurring obligations that are easy to forget.
The most useful test is to imagine a normal month, not an ideal one. Add the income dates first, then place the fixed commitments around them. After that, look at the gaps between those events. If the calendar view immediately helps you notice a tight stretch, the app is doing something valuable that a conventional category list may not show as clearly.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Who benefits from the visual layout
I can see Budget Calendar working well for a person who gets paid on a predictable schedule but has many expenses scattered through the month. It also suits households that plan manually and want a shared mental picture, even if only one person enters the information. The calendar can act as a simple planning board for rent, utilities, loan payments, school costs, travel, and occasional purchases.
It may also help someone who is trying to stop relying on memory. Instead of keeping a subscription or annual bill in the back of my mind, I can place it where it belongs in the flow of the month. That does not automatically make the payment affordable, but it makes the decision harder to overlook.
On the other hand, people who expect their accounts to populate themselves may find the approach demanding. The app’s strength is deliberate planning, so I need to enter and review information rather than waiting for a complete financial picture to appear without effort.
The questions I would ask before installing it
First, do I want planning or reporting? If I mainly need a record of completed purchases, a standard expense tracker may feel more natural. If I want to see whether upcoming obligations fit around incoming money, Budget Calendar is more closely aligned with that goal.
Second, am I comfortable with manual budgeting? A calendar is only as useful as the events I keep current. A forgotten bill or an outdated amount can make the forecast misleading. That is not a flaw unique to this app, but it is an important trade-off compared with services built around automatic account information.
Third, will I use a compact, focused tool instead of a broad personal-finance suite? Budget Calendar is easier to understand when I treat it as a planning instrument, not as an all-purpose financial command center.
Where the calendar approach wins in everyday use
The calendar earns its keep when I need to compare several commitments by timing rather than simply review spending after the fact. I’d use it to distinguish fixed obligations from flexible plans, then make one deliberate adjustment before the next payday if the schedule looks crowded. That everyday test helps show where this format is genuinely more useful than a standard expense list.
Planning the period between paydays
A realistic scenario shows the app’s best use. Imagine I receive income near the beginning and middle of a month. Rent is due shortly after the first payment, a utility bill arrives several days later, and a recurring service is charged just before the second payment. None of those expenses is surprising individually. The problem is the order.
By placing each item on the calendar, I can see whether the first payment has to carry too much of the month. I might decide to postpone a nonessential purchase, reserve money earlier, or move a payment when that is possible. A category budget could eventually reveal the same pressure, but the calendar gives me the timing immediately.
One practical habit I would recommend is entering income before expenses. That creates the frame for the month. Then I would add fixed commitments, followed by flexible spending plans. This order prevents me from treating every available day as spending space before the unavoidable payments have been accounted for.
Separating known commitments from optimistic guesses
The calendar is also useful for distinguishing certainty levels. A rent payment has a known date and usually a stable amount. A grocery plan or weekend outing is more flexible. I would use the calendar to place both, but I would mentally treat them differently: fixed events protect the budget, while flexible events are the first candidates for adjustment.
This is a small but important insight. Many budgets fail because a planned expense is treated as guaranteed income in reverse. Seeing an item on a date can make it feel official, even when it is only an intention. I found it more useful to review each entry and ask whether it is a bill, a target, or a wish. That keeps the visual plan from becoming overconfident.
Making irregular expenses less disruptive
Annual renewals, seasonal purchases, and occasional repairs are difficult to manage when I only look at the current month. A calendar gives these events a place in the broader plan. Even if I do not know the final amount precisely, recording the expected timing can remind me to prepare before the expense becomes urgent.
For example, I might mark a yearly payment several weeks ahead and then create smaller preparation entries leading toward it. The point is not to pretend the app has saved the money automatically. The point is to turn a distant expense into a visible planning task. That workflow is more useful than waiting for the charge to appear and then wondering why the month suddenly feels expensive.
Using the month as a conversation tool
Money discussions can become vague when one person says there is “not enough left” and another asks where it went. A dated plan gives the conversation something concrete. I can point to the sequence of commitments and discuss which items are fixed, which can move, and which should be removed.
This can work for couples, families, or anyone helping another person organize bills. The calendar does not replace agreement, but it can reduce the emotional distance between a general concern and a specific choice. That is one of the less obvious strengths of a date-based budget.
What I would check during a weekly review
I would not wait until the end of the month. A short weekly review is enough to compare planned events with reality, remove anything that no longer applies, and look ahead to the next payday. The important detail is to update the plan after a change, not merely notice that the plan was wrong.
I would also avoid filling the calendar with every tiny purchase. That can turn a planning tool into a tedious diary. I would reserve it for income, recurring commitments, larger planned spending, and the flexible amounts that could affect the balance between paydays. Smaller purchases can be handled through a separate method if detailed tracking is necessary.
What the app’s history suggests about its role
Budget Calendar was released on May 17, 2013, and the current version is 1.69. That history gives me a useful expectation: I would approach it as a focused budgeting utility rather than assume it follows every current trend in personal-finance design.
Its store summary describes easy budgeting planning on a calendar, and the short description calls it Budget Calendar. Those descriptions are brief, but they accurately point to the central experience: the app’s identity is the calendar itself, not a collection of unrelated financial tools.
The app has an average rating of 4.8 from 481 ratings, with 189 written reviews, and it has passed 10K+ installs. Those figures suggest that the focused concept has found an audience, although popularity alone would not decide the purchase for me. I would still choose it based on whether date-based planning matches my habits.
Where the price makes sense
At $4.95, the app asks for a small one-time-style purchase decision rather than presenting itself as an obviously free utility. I see that as reasonable only when the calendar solves a recurring problem. If it helps me avoid missed payments, reduce last-minute spending, or plan around uneven cash flow, the cost is easy to justify.
If I am merely curious about budgeting and rarely review plans, even a low price may be wasted. A free alternative that I already open regularly can be better than a paid app that matches my needs perfectly in theory but never becomes part of my routine.
What I would not expect it to replace
I would not choose Budget Calendar as my only tool if I need detailed transaction categorization, extensive reports, investment monitoring, debt analytics, or automatic account reconciliation. Those needs belong to broader personal-finance services or a combination of tools.
I also would not expect a calendar to tell me whether a purchase is emotionally or practically worthwhile. It can show that an expense falls between two bills, but it cannot judge the quality of the purchase. The user still has to make the financial decision.
When a different category is better
A spreadsheet is a stronger option for someone who wants complete control over formulas, custom reports, and long-term historical analysis. It can be shaped around unusual income patterns, but it requires more setup and maintenance.
A bank-connected finance service is more suitable for someone who wants transactions imported and categorized with minimal manual entry. The trade-off is that the experience may be broader and less focused on a clean calendar plan. A conventional expense tracker is preferable when the main goal is understanding where money went, while Budget Calendar is preferable when the main goal is deciding what can happen next.
There is also a place for a simple paper calendar. For a person who dislikes apps or shares planning with someone who will not use the same device, paper may be easier. The advantage of this app is not that a digital calendar is automatically superior; it is that a dedicated finance calendar can keep the plan available in a repeatable format.
The cost of switching from an existing method
Moving from a spreadsheet or notes app has a hidden cost: rebuilding the structure. I would not try to transfer every historical purchase. I would start with the next income event, the fixed bills that follow it, and the recurring expenses that most often cause surprises. That produces a useful working calendar without turning setup into a major project.
Someone moving from a bank-connected service may experience a different kind of friction. The change is not just visual; it is behavioral. Automatic records encourage checking what happened, while a calendar encourages entering what is expected. I would only switch if I was willing to take responsibility for keeping future events accurate.
A good transition method is to run both approaches briefly, using the existing tool for transaction history and the calendar for forward planning. During that period, I would compare the calendar with actual account activity and adjust amounts or dates. Once the calendar consistently answers my main questions, I could decide whether the older tool is still necessary.
Privacy and attention trade-offs
A manually planned calendar can feel calmer than a stream of notifications and categorized transactions. I am looking at the obligations I chose to plan, not constantly reacting to every small purchase. For some people, that makes budgeting less overwhelming.
The opposite is also possible. If I prefer automation because manual entry feels like work, the same simplicity can become a limitation. The app rewards attention in short, regular sessions. It is not a set-and-forget solution, and I would not recommend it to anyone unwilling to check dates and amounts as circumstances change.
Compatibility and practical expectations
The listed minimum operating system is 7.0, and the content rating is Everyone. That makes the app broadly approachable from an age-rating perspective and suitable for people using older compatible devices. I would still think about the age of my phone and my comfort with the app’s established design before paying for it.
Because the product has a focused identity and a long release history, I would judge it by reliability and usefulness rather than expect a constantly changing interface. The right mindset is to buy a tool for a specific job: arranging expected money events on a calendar and reviewing the space between them.
My clear recommendation
I recommend Budget Calendar to students, households, freelancers, and regular earners who understand their finances through dates. It is especially compelling when several predictable commitments compete for the same paycheck, or when occasional expenses keep appearing as unpleasant surprises.
I would skip it if my priority is automatic bank imports, deep financial reporting, detailed spending history, or investment management. In those cases, a broader finance category will fit better, even if it offers a less direct calendar view.
For everyone else, I would begin with a deliberately small plan: enter the next income dates, add the fixed bills, mark the flexible spending decisions, and review the upcoming week regularly. That test reveals the app’s value quickly. If the calendar helps me make better choices before money leaves my account, the $4.95 price is sensible. If it feels like another list I will forget to maintain, no rating or install count can make it the right choice.
After using it this way, my view is that Budget Calendar succeeds because it keeps budgeting tied to real life: dates, deadlines, paydays, and the uncomfortable gaps between them. It is not trying to be every kind of finance app. Its best feature is the discipline of seeing the month before the month happens.
That narrow focus is both its advantage and its boundary. I would recommend it as a practical planning companion, not as a complete financial system. If that distinction matches what you need, Budget Calendar is a focused purchase that can turn vague money worries into specific calendar decisions.
Pros
- Clear calendar view makes upcoming income and expenses easy to track.
- Supports planning bills ahead to reduce the risk of missed payments.
- Useful for comparing expected and actual spending over time.
- Recurring transactions save time when managing regular bills and income.
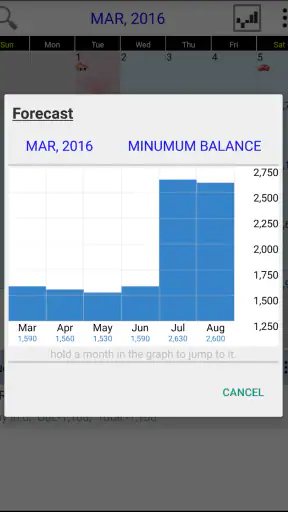
- Helps visualize cash flow before making larger purchases.
Cons
- May require regular manual updates to keep balances accurate.
- Advanced budgeting tools may be limited compared with full finance apps.
- Too many entries can make the calendar feel crowded on smaller screens.
- Users may need time to learn the app’s planning and navigation features.
- Features and availability can vary between Android and iOS versions.
FAQs for Budget Calendar
What is Budget Calendar and who is it designed for?
Budget Calendar is a personal finance app that helps you organize income, bills, expenses, and savings goals on a calendar-based timeline. Instead of viewing transactions only as a list, you can see when money is expected to arrive and when payments are due. It can be useful for students, families, freelancers, and anyone who wants a clearer picture of upcoming cash flow.
How does Budget Calendar help me manage my monthly finances?
The app lets you add recurring income, bills, subscriptions, and everyday expenses to specific dates. Once your entries are organized, you can review your expected balance throughout the month and identify periods when spending may be higher than usual. This makes it easier to plan payments, avoid surprises, and decide how much money can safely be allocated to savings or discretionary purchases.
Can I customize recurring bills, income, and budget categories?
Yes, Budget Calendar is built around customizable financial entries. You can generally create items for regular salary payments, rent, utilities, loan installments, subscriptions, groceries, transport, and other categories that match your lifestyle. Recurring items are particularly convenient because they reduce repeated data entry, although you should still review them whenever an amount, payment date, or billing frequency changes.
Does Budget Calendar connect to my bank account automatically?
Budget Calendar is primarily intended for planning and manually recording financial activity, so automatic bank synchronization may not be available or may depend on the platform and version you install. Before downloading, check the current store description and privacy information to confirm supported integrations. If you prefer hands-on control and do not want to share banking credentials, manual tracking can be a useful advantage.
Is Budget Calendar free to use, and are there any privacy concerns?
The availability of free features, premium tools, advertisements, or in-app purchases can vary between Android and iOS versions and may change with updates. Review the store listing before installation to understand the current pricing. Because financial information can be sensitive, also read the app’s privacy policy and check what data is stored, collected, or shared before entering detailed personal or account information.

Budget Calendar
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mnefedov7@gmail.com, visit http://www.mishell.ca/, or review their http://mishell.ca/docs/privacy-policy.html.










